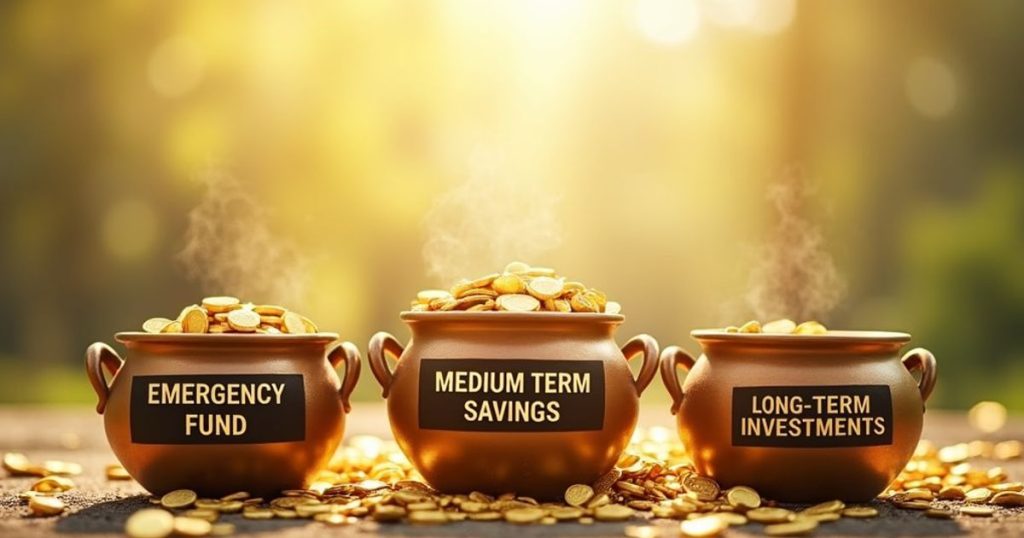
As the new tax year approaches, financial planners urge households to review their approach to investing and savings. Market volatility and rising costs have exposed weaknesses in many financial plans. Experts now support the three-pot system. This time-based structure helps reduce risk, improve discipline, and build long-term financial stability.
Securing foundations before taking risks
The first pot is about resilience rather than returns. Advisers widely recommend holding three to six months of essential expenses in accessible cash. This buffer protects against redundancy, urgent medical bills, or sudden home repairs. Without adequate liquidity, investors may be forced to sell assets during market downturns, locking in losses at the worst possible time.
The second pot targets predictable, medium-term goals within three to five years. This can include a home deposit, education fees, or other planned costs. Because the timeline is short, preserving capital becomes more important than chasing high returns. Low-risk savings vehicles and tax-efficient accounts often fit this segment.
Critics argue that holding substantial cash reduces overall portfolio returns. While there is truth in this, empirical evidence shows that investors with structured liquidity are less likely to panic during volatility. This reserve supports disciplined decision-making and lays a stronger foundation for future investing.
Strategic allocation powers long-term growth
The third pot is where long-term growth potential is pursued. Funds intended for at least five years or more may be directed into diversified equities and other growth-oriented instruments. Historically, global stock markets have delivered higher returns than cash over extended periods, though short-term fluctuations remain inevitable. Investors must therefore align allocations with individual risk tolerance.
Compounding returns in this pot can significantly enhance wealth over time. Tax-efficient wrappers like ISAs and diversified portfolios help optimize performance and control risk. Some investors complement traditional markets with alternative assets for broader exposure, though these introduce liquidity considerations.
Advisers emphasize disciplined contributions, consistent review, and professional guidance. When applied with rigor, the three-pot structure elevates investing from reactive behaviour to a deliberate, research-based strategy for sustainable financial growth.